The EMI date passed. The money was meant for it, but a school fee, a hospital visit or a late salary got there first. Now there is an SMS on your phone and a knot in your stomach.
So what happens if you miss a personal loan EMI? Usually less than you fear, if you act quickly.
Quick answer: A missed EMI usually brings a late-payment charge, reminders from your lender and, if it stays unpaid, a mark on your credit report that can lower your score. The size of each depends on your loan terms. Acting early keeps all three small.
What a missed EMI sets off
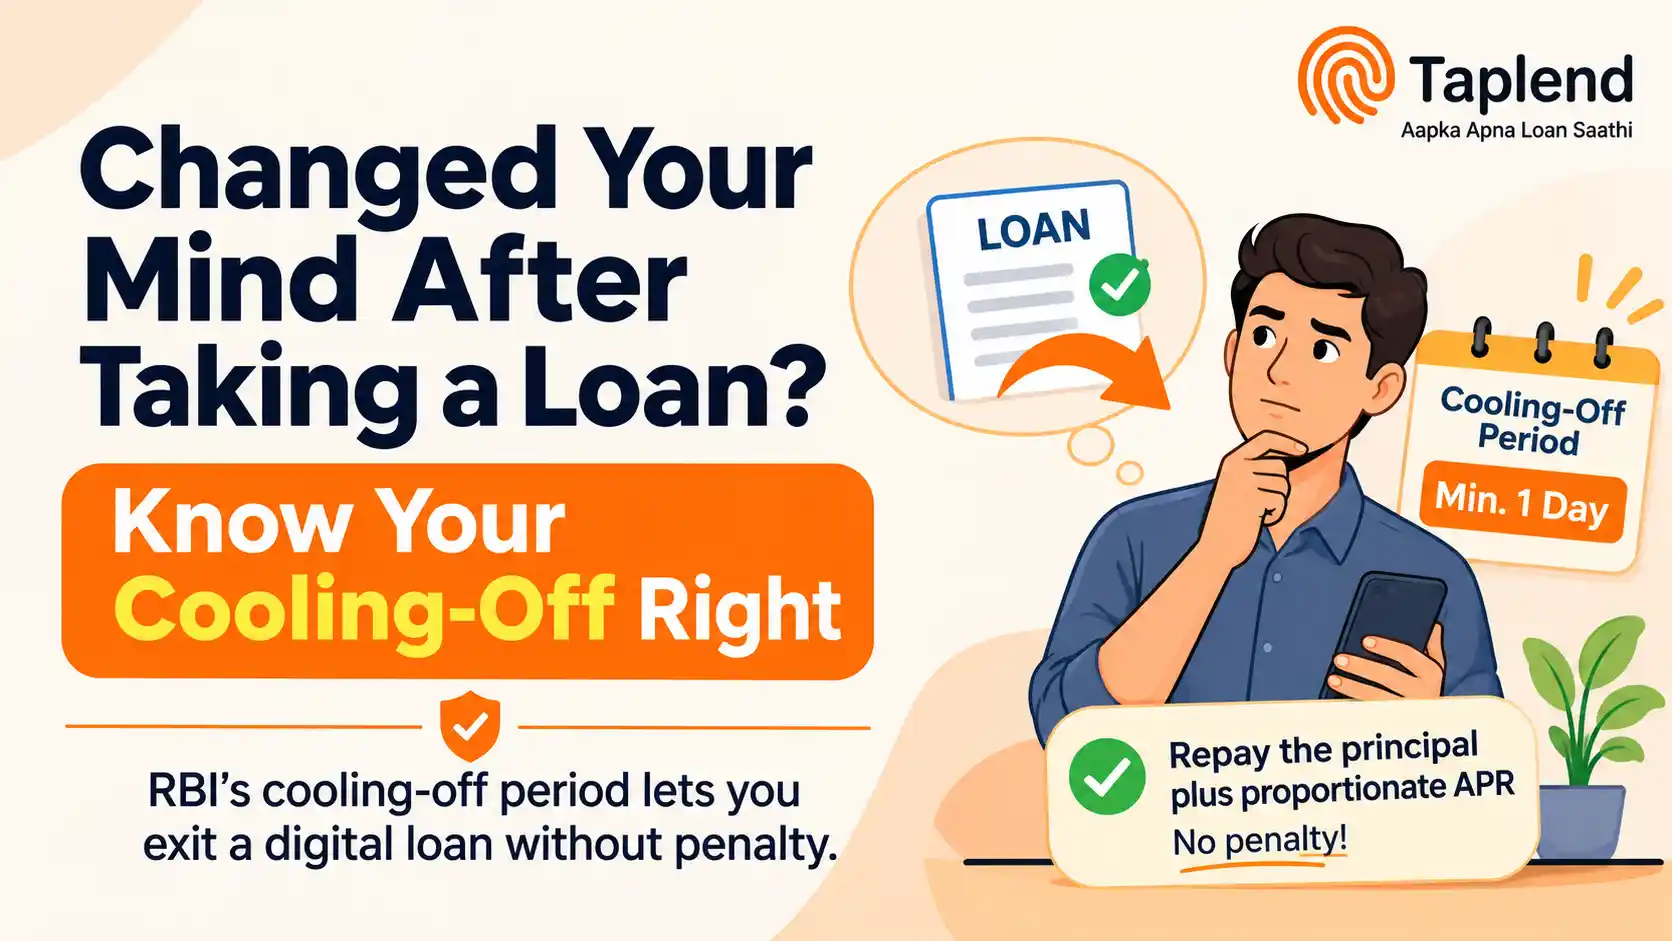
A charge. Lenders add a late-payment or penal charge. Look for the exact rupee amount in your Key Facts Statement (KFS), the cost summary a digital lender shares before you accept a loan. RBI's rules say penal charges cannot be added as extra interest on your rate, no interest can be charged on the penal charge itself, and reminders must state the applicable penal charge. A fee not in your KFS cannot be added later without your consent.
Reminders. Expect SMS, app alerts, and calls. They are routine.
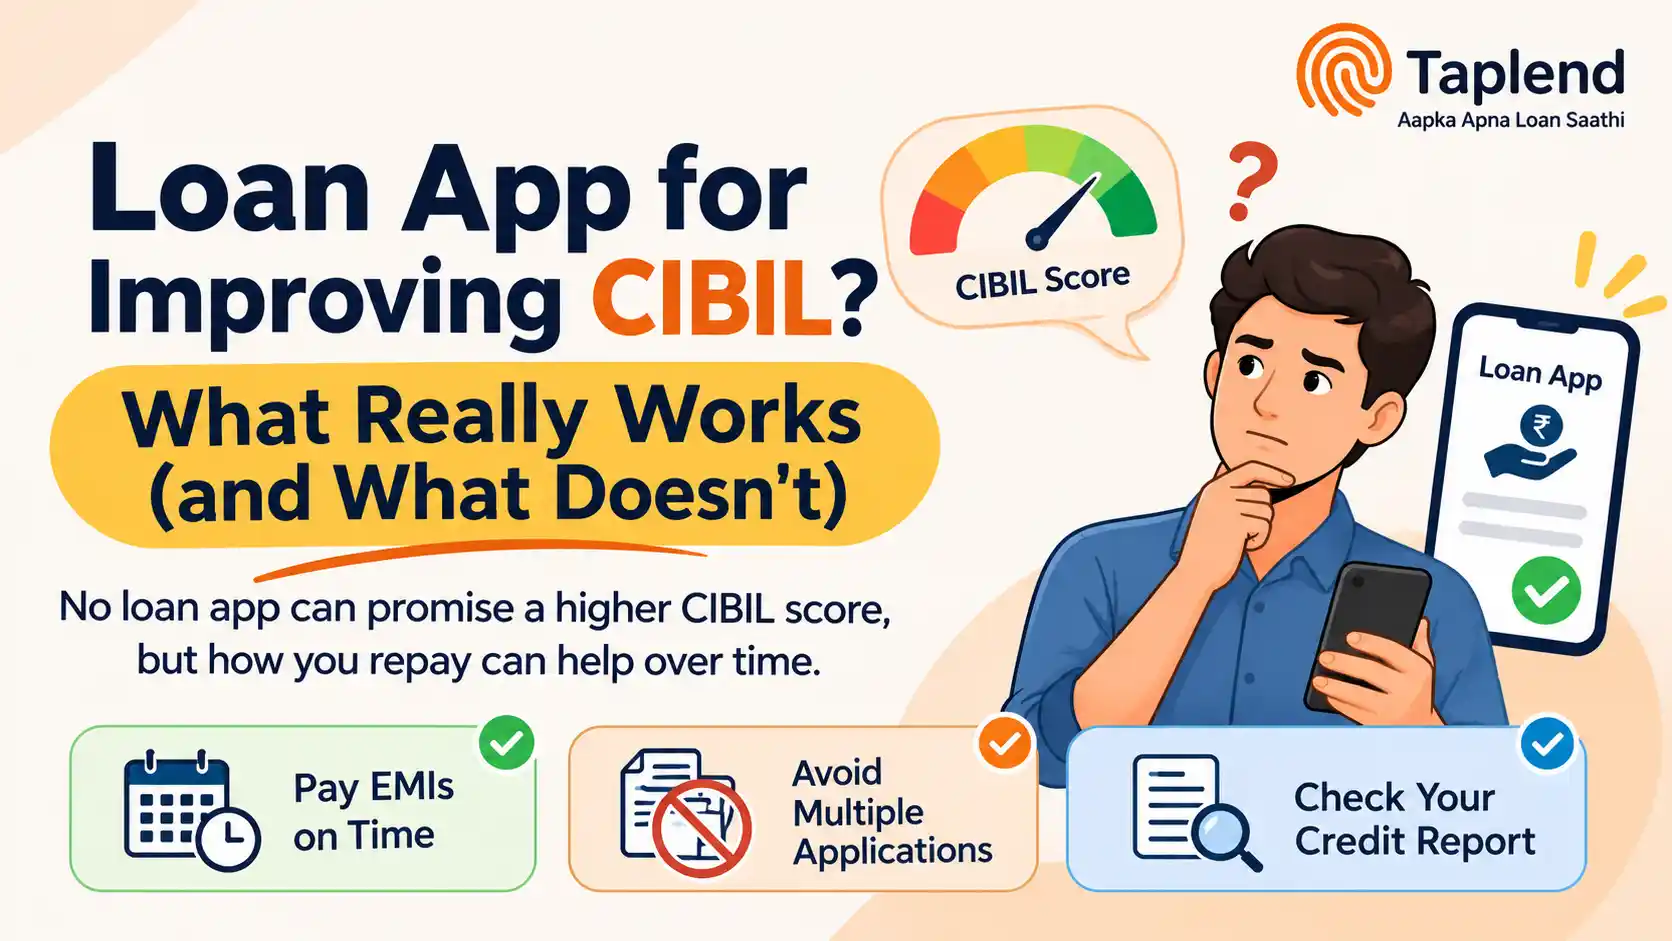
Your credit report. Lenders report repayment status to credit bureaus such as CIBIL, Experian and Equifax. A missed EMI can pull your score down, which matters when you next apply for a loan or card. How far it falls depends on your wider history, and nobody can promise an exact number.
Your first 48 hours
- Find the real amount: Check the EMI plus the charge, in rupees. A short delay costs less than a long one, so pay quickly.
- Speak up before the next due date: if you cannot pay in full. Ask three things: what is the exact charge, can I pay in two parts, and is a revised date possible? A borrower who calls early is easier to help than one who goes quiet.
- Be careful with settlement: Paying less than the full dues may close the loan, but it is flagged on your report and looks worse than full repayment.
- Do not borrow from another app to pay this EMI: One missed payment can quietly become two loans and two EMIs.
- Fix the cause: If your EMI falls just before payday, ask whether the date can move. Keep one EMI as a cushion in your account.
Thinking about a personal loan? Pick an EMI your take-home pay can carry after rent and bills, check eligibility on the Taplend app, and read the KFS before you accept.